
A Hotter August CPI Builds Rate Hike Momentum
First, let’s clarify that any attempt to predict the Federal Reserve’s actions this week is, at best, an educated guess.
Fed Chair Kevin Warsh has struck a hawkish tone, and the odds of a quarter-point increase in the fed funds rate are 87%, according to the CME Group. It was 59% on September 4.
But unlike past Fed chairs, the new Fed chairman opposes what economists call ‘forward guidance.’ So, investors are left guessing.
So, how did the August CPI report come in? According to the U.S. Bureau of Labor Statistics (BLS), consumer prices rose 0.4% in August, matching expectations, amid a 2.1% increase in energy.
But investors focused on a 0.3% increase in core CPI, which excludes food and energy. That was above the 0.2% forecast.
The CPI is up 3.4% from one year ago, led by energy prices.
However, the core CPI slowed to an annual rate of 2.4%, the slowest of the cycle, suggesting that higher gasoline and diesel prices aren’t bleeding into the broader economy. Of course, that’s not true of all categories. For example, airfares are up 23% from a year ago.
But for the most part, we have yet to see the spike in gasoline prices seep into the broader price level, and that’s good news for consumers and investors.
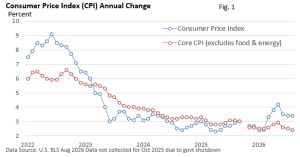
Figure 2 illustrates what’s happening to gasoline prices. On average, prices rise in winter and spring, peak in summer, and gradually recede after Labor Day.
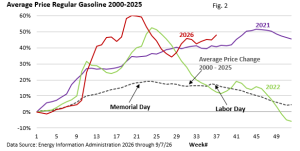
Figure 2 also reflects this year’s sharp rise and contrasts it with 2021, when prices were recovering from lockdown-era lows, and 2022, when Russia’s invasion of Ukraine forced a steep but temporary rise in gas prices.